The energy think tank Ember estimates that only around 3% of global data center capacity will be able to shift its electricity use by 2030. In new research, it found that 87% of data centers will still run cloud services and corporate IT systems alongside AI inference, so their consumption cannot easily be paused or moved. Data centers dedicated to AI training, a better fit for load shifting, will make up 13% of the market.
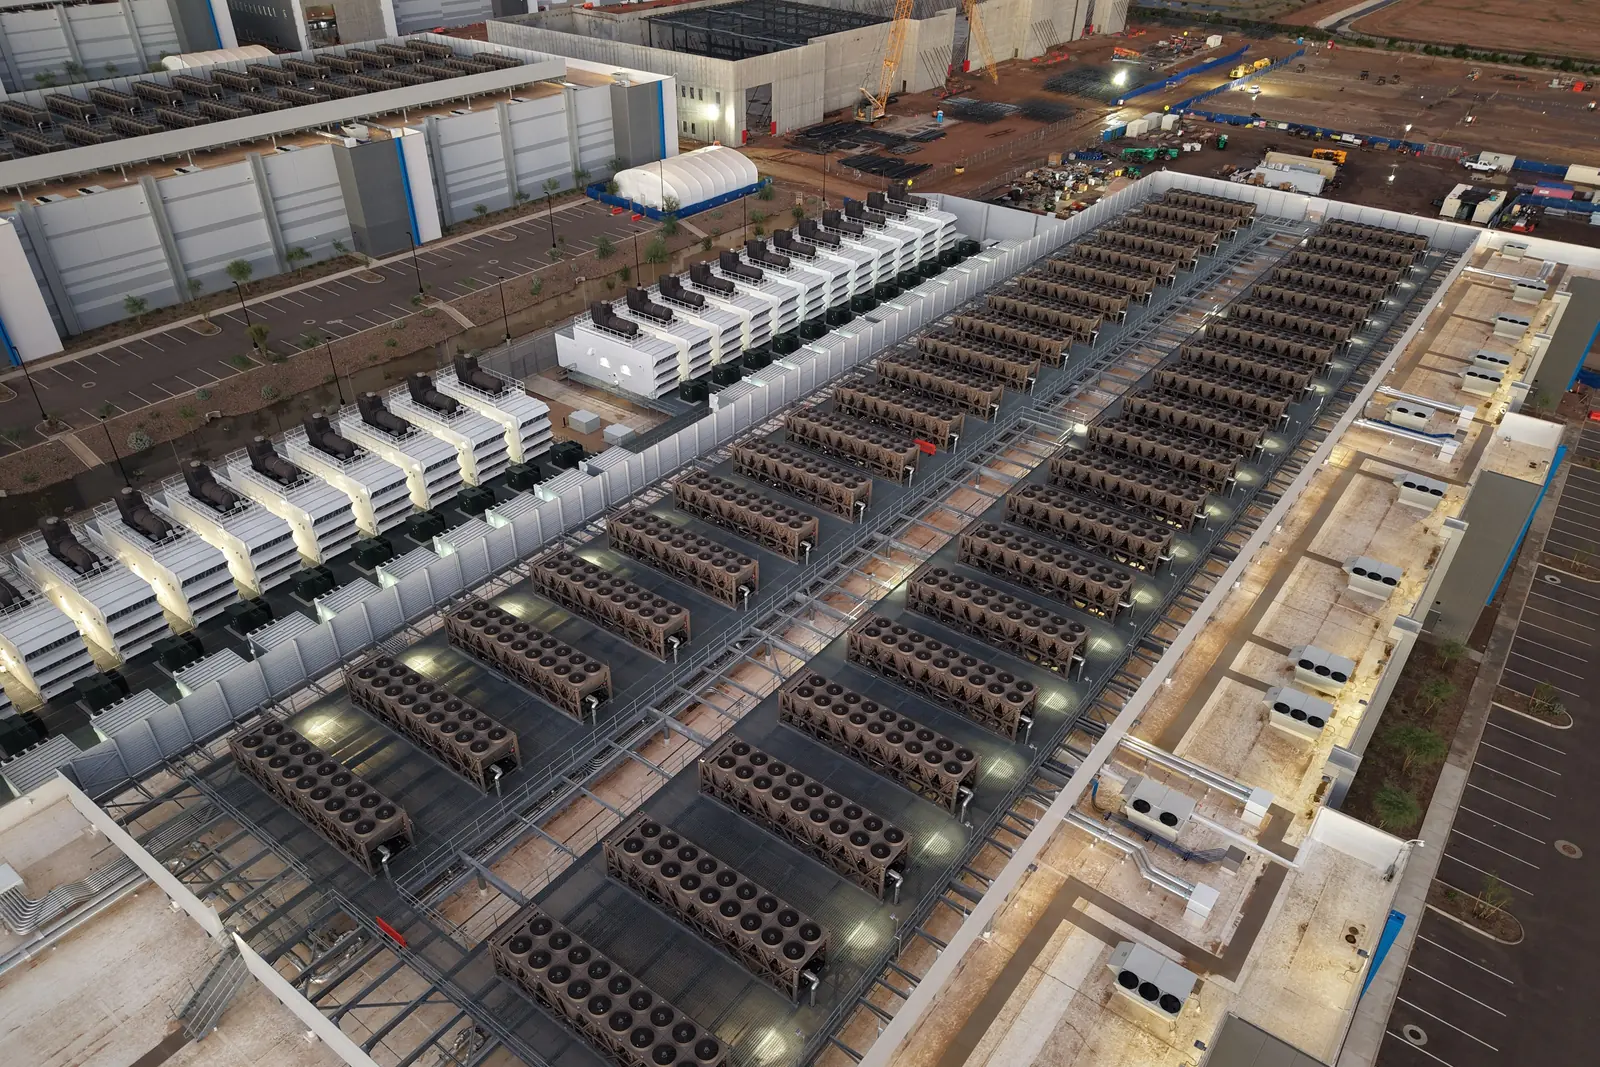
The finding does not necessarily undermine the case for flexible data centers. It does suggest that scaling them will depend less on rescheduling computing and more on alternative power supplies, which makes the research a potential boost for onsite options such as gas turbines and batteries.
Load shifting trims peak demand by fractions of a percent
Ember analyzed nine major data center markets, including Texas, California and New York. In the U.S. and most other countries, load shifting would reduce peak demand by between 0.1% and 0.6% by 2030. Texas contributes the most among U.S. markets, with up to 0.4%. In Ireland and Malaysia, where data centers make up a larger share of peak demand, the potential reduction is higher, at around 1.5%.
The report says the biggest potential for grid relief is a combination of load shifting and onsite generation. Onsite generation gives more relief at peak. Load shifting helps get more out of the existing grid and avoids new infrastructure that would otherwise be rarely used.
The Texas example
Ember looked at two AI data centers in Texas, Stargate Abilene and Comanche Circle, which together account for about 5.6 gigawatts of new load online by 2030. At the typical U.S. data center utilization rate of 48%, they would draw an average of 2.7 GW. Both plan to use an ERCOT grid connection as well as onsite generation.
Load shifting at the two sites could relieve .55 GW during a grid stress event. Moving entirely to onsite generation could provide the full 2.7 GW of relief, equal to 2% of ERCOT's predicted 2030 peak load.
Non-firm interconnection and the battery market
The Federal Energy Regulatory Commission in June directed grid operators to justify or revise their rules for connecting large loads, following orders from the Department of Energy to speed those connections. ERCOT and SPP have already adopted non-firm interconnection pathways. FERC rejected PJM's data center curtailment plan, and PJM is revamping its framework ahead of a November 16th filing deadline.
Research platform Currence says non-firm interconnection rules could create a U.S. battery market of up to 285 GWh by 2035. That modeling assumes half of forecast data center load uses some form of flexibility and relies on batteries to cover curtailments. PJM accounts for more than half of the projected storage market.
Currence also expects curtailment events to grow longer and more frequent as each flexible data center comes online, so the standard four-hour battery may fall short. In ERCOT, a uniform rule spreading curtailments evenly would require about 1.3 hours of storage per data center by 2030. A last-in-first-curtailed approach would require at least 5.3 hours for the newest facilities. Under that approach in PJM and SPP, duration needs could reach seven hours by 2035.
For durations up to eight hours, Currence says lithium-ion batteries remain the technology to beat. Beyond eight hours, some non-lithium storage technologies are becoming cost-competitive.